Diaspora Connect, 26 August 2026, 8 min read
Why African Diaspora Investments Stall: A Coordination Problem
The African diaspora's money is real and it moves every month. What keeps getting lost is the share meant to build something, because each investor checks every deal alone.
In February 2011, two World Bank economists, Dilip Ratha and Sanket Mohapatra, tried to measure something nobody had measured: how much the world's diasporas save each year. For the African continent, using 2009 data, their preliminary estimate was nearly $53 billion a year, of which $30.4 billion belonged to the Sub-Saharan African diaspora.
That estimate is now more than fifteen years old, built on migrant numbers from 2009, and the diaspora has grown since. Treat it as an old, rough marker, not a current figure. It is still the most specific published estimate of African diaspora savings we could find. It is not a trillion dollars, and it does not need to be. Next to it sits a second, more recent number. The World Bank's Migration and Development Brief 40 put remittances to Sub-Saharan Africa at $54 billion in 2023, and the Bank's latest data put them at about $57 billion in 2024.
The money is real and it moves every month. Most of it does exactly what it was sent to do: school fees, hospital bills, rent, a roof. That is not a failure. Those transfers keep households stable, and the people who send them know it.
The problem sits in the smaller share that is meant to build something: a farm, a building, a stake in a business. That share keeps getting lost. The reason is not a shortage of money or courage. It is that each investor acts alone, against costs that only a group can carry.
Who the diaspora is
The International Organization for Migration's World Migration Report 2024 counts over 19.5 million Africans living outside Africa in 2020, most of them in Europe. It counts around 21 million Africans living in another African country. The diaspora is not only a London or Houston phenomenon. A Kenyan in Kigali and a Ghanaian in Lagos face the same problem as a Nigerian in Manchester: their money can cross a border faster than their ability to check what it buys.
These are physicians, nurses, engineers, drivers, accountants, teachers and shop owners. Their combined expertise is wide. Their capital, per person, is mostly modest. And almost all of them invest, when they do, one at a time.
Six ways one investor loses
The losses follow a small number of patterns. Each is predictable once you see the investor as a single person trying to read an asset from far away. (For what the evidence says about each, see why diaspora-led African investments fail.)
The trusted relative. Capital moves on the strength of a relationship, not a contract. The relative is rarely dishonest. They live in a household where money has many urgent claims, and the line between the business and the family was never written down. When a parent falls ill, the money moves. It was never separate.
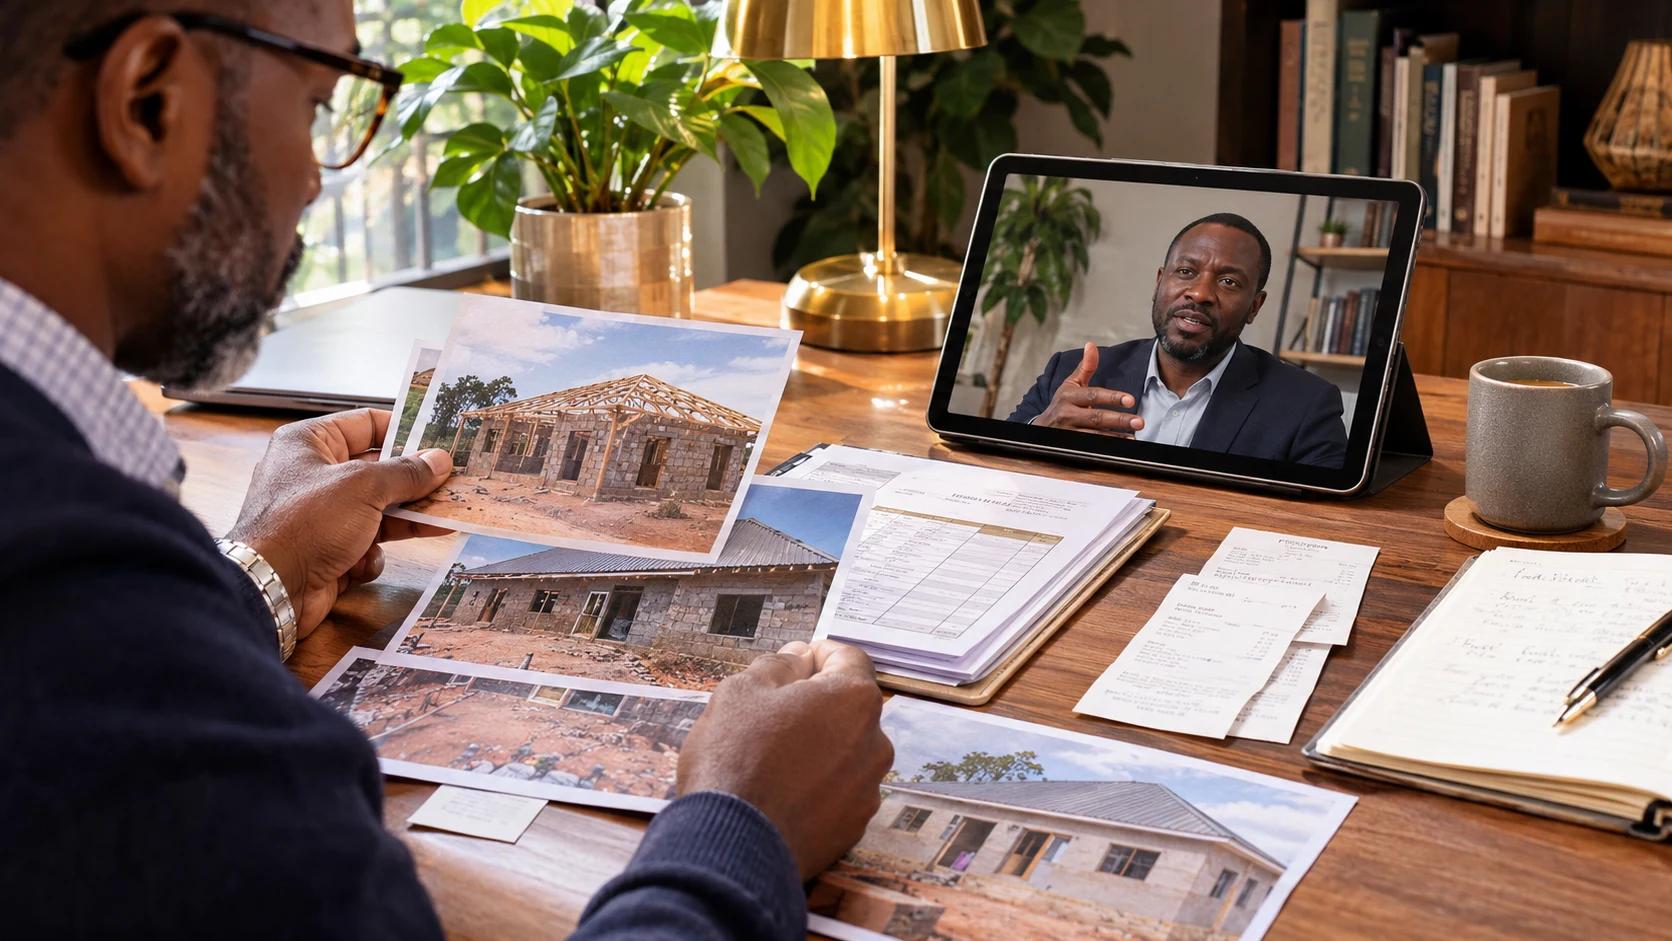
The ghost asset. Land with more than one buyer. Equipment that was leased, not bought. Where a title or company record cannot be checked from abroad, an asset can be sold to more than one person before any of them finds out. (If the asset is land, read buying land in Nigeria from abroad before you pay.)
The project that cannot pay you back. The business works, but returns cannot leave. A currency shortage, an approval process for repatriating dividends, or a tax the investor's accountant at home did not know about holds the money in place.
The disappearing partner. The local manager who was essential at signing stops answering six months later. Without someone on the ground, the investor cannot compel a meeting, let alone an account.
The missing information. Before any of this, the investor needs to check a contractor, a price, a regulation. The tools an American investor takes for granted at home, public filings and comparable sales and contractor reviews, are thin or absent for the asset in question.
The enforcement gap. Being legally right is not the same as being paid. Cross-border judgments are slow and costly to enforce. Often recovery costs more than the loss, so the investor absorbs it and says nothing. That silence is why the same patterns keep catching new people.
Look at the six together. None of them is about one investor being foolish. Each is a cost: of verifying, of monitoring, of enforcing. Each cost is roughly fixed per deal. That is the hinge of the argument.
The cost is fixed; the investor is small
An illustrative example, with made-up numbers. Suppose a proper title check on one property costs $2,000: a lawyer, a registry search, a survey, an inspection. For an investor putting in $20,000, that is 10% of the deal before anything is bought. Most people, looking at that, do less checking than they should. Some do none.
Now suppose two hundred investors share the same check on the same asset. It costs each of them $10. The lawyer has a reason to do careful work, because the group will hire her again. The result is a record more than one person can read. A seller who has already sold a plot once finds it harder to sell it again to someone who can see that record. AfroSynergy offers no investment or pooled products.
This is how functional capital markets work everywhere. An index fund investor does not read five hundred annual reports. Auditors, regulators, analysts and journalists do that work, and its cost is spread across millions of people. The African diaspora investor has no such layer. So each one pays the full price of checking, or skips it.
The failures are what that arithmetic produces. They are not evidence that diaspora investors are careless, or that the trust they rely on is fake. The trust is real. It just cannot be read by anyone outside the relationship. The chamas, susus and stokvels that pool savings at home show the same pattern: discipline that works inside the group and is invisible outside it.
Diasporas that built the channel
Other diasporas faced a version of this problem and built a channel for it. In a 2010 paper in the Journal of International Commerce, Economics and Policy, Suhas Ketkar and Dilip Ratha reported that Israel, issuing every year since 1951, and India, on three occasions since 1991, had raised over $35 billion through diaspora bonds.
The mechanism is what matters. A bond buyer in Toronto did not need to inspect a road or a power line. A state stood behind the instrument, and a single issuer did the checking once for everyone. The same paper notes that diaspora bond issuance elsewhere had remained meager.
These cases are not templates. Israel and India could issue sovereign debt to one large diaspora each. The African diaspora comes from fifty-four countries with fifty-four sets of registries, currencies and rules. What the cases do show is narrower: when someone builds a layer that makes the investment readable once, the money follows.
The objections worth taking seriously
"You left. Why should you organize our economy?" Continental Africans ask this, and they are right to. Diaspora coordination that treats local operators as project managers for foreign capital will reproduce the extraction it claims to replace. Local partners have to be full counterparties, with their own capital and decision rights, because they know things the diaspora investor does not.
"We have tried this before." Many returnees and remote investors have gone home with conviction and come back quieter. A structure that asks less of each individual, and spreads both the checking and the exposure, answers that history better than another call for courage.
"Not everyone has $50,000." Most of the diaspora does not. A structure built only for the wealthiest members will be a club, not infrastructure. Any serious attempt has to work for the nurse with a few hundred dollars as well as the surgeon with far more, under the same documents and the same protections.
"Is this another outside prescription?" It can be. The test is visible in the design: who sits on the boards, who owns the records, who pays the fees, and whether local partners can use the same tools on the same terms.
What to do this week
The coordination layer does not exist yet at the scale this problem needs. Part of building it is individual: knowing exactly what you already hold.
List every asset or stake you have back home. Next to each one, write the document that proves it is yours, where the original is, and which registry would confirm it. Where you cannot fill in a line, you have found the gap. Ask a lawyer in that market what it would take to close it. Then find two other people from your community who are facing the same question, and compare notes before anyone sends money. If you are planning a move home as well, read how to find business partners you can trust in Nigeria, Kenya or Ghana.
AfroSynergy connects international buyers with African exporters. Listings open on 15 January 2027. To source a product or find a counterparty now, send us an enquiry.
Ready to Explore Opportunities?
Discover funding opportunities, partnerships, and projects across Africa. Founding-cohort access is by invitation during pre-launch.
Comments
Sign in to leave a comment. Comments are moderated.
Keep reading
Sourcing from Africa?
Listings open on 15 January 2027. Tell us what you need to source and we will come back to you.
Or get new guides by email.
By subscribing you agree to our Privacy Policy. Unsubscribe anytime.