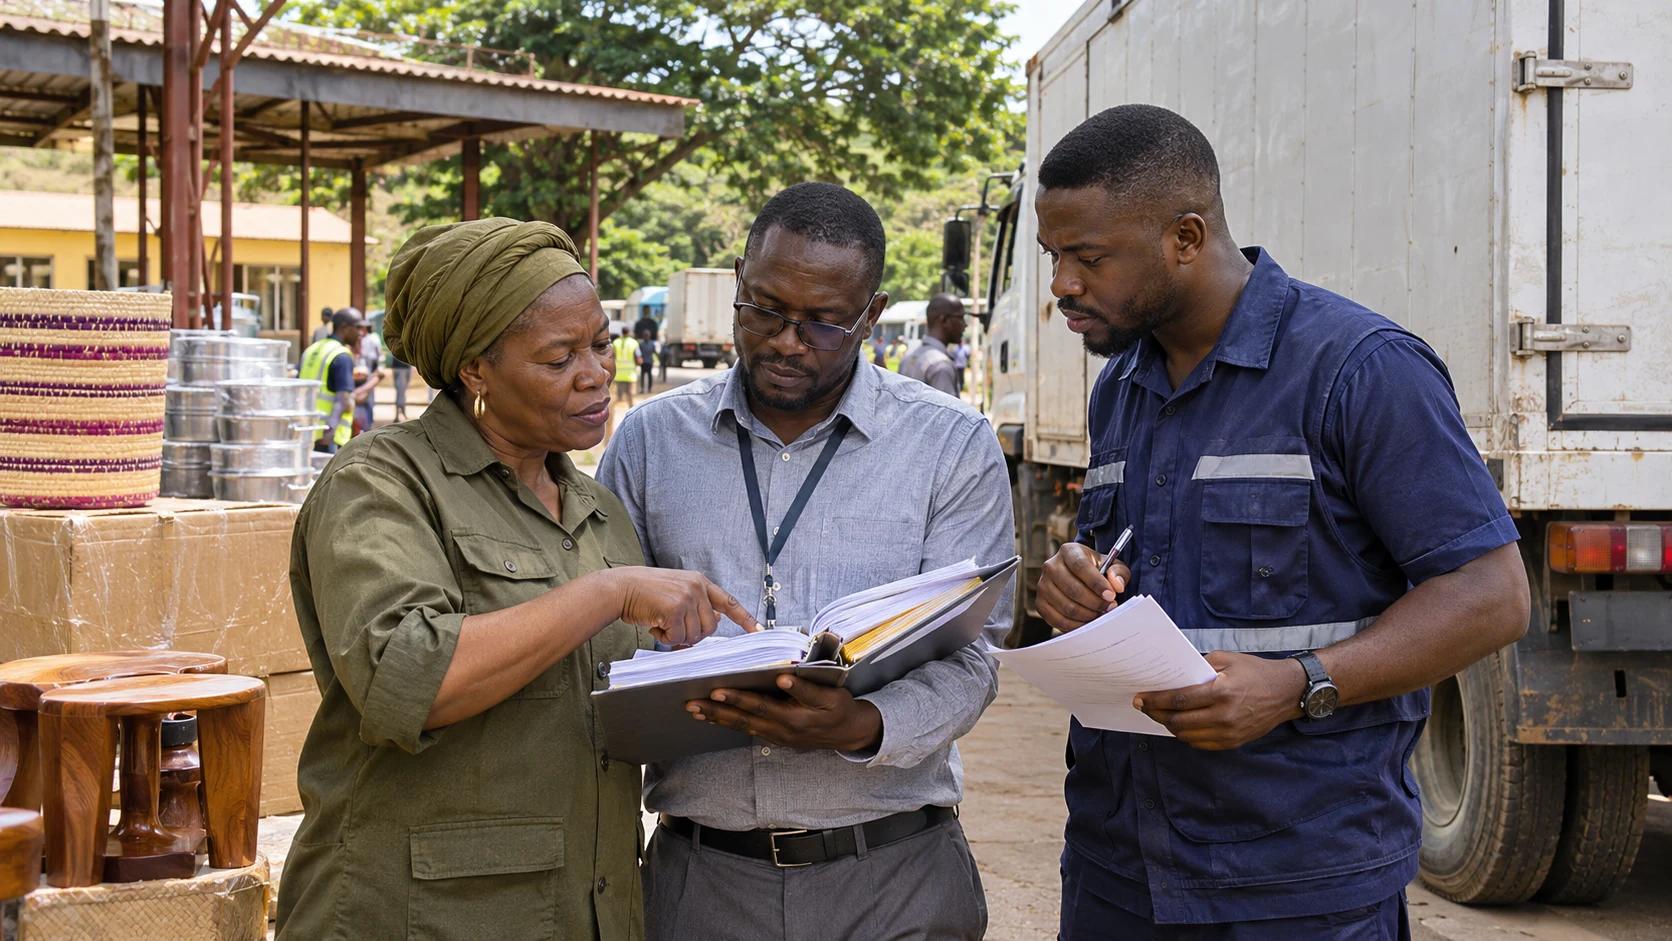
A chama, a susu and a stokvel are three names for the same old idea: people who know each other pool money on a fixed schedule and hold each other to it. In Kenya, a chama is an informal savings group run by its members. In Ghana, susu usually means a collector who takes small daily deposits and returns them at the end of the month for a fee. In South Africa, a stokvel is a community savings group whose members contribute regularly. All three work without collateral, credit scores or courts. For anyone extending trade credit in Africa, that is the interesting part: the discipline is real, it is widespread, and almost none of it is visible to a lender or a supplier outside the group.
This essay looks at how these groups enforce repayment, what that teaches about business-to-business credit, and where the analogy breaks.
How big they are
These are not marginal institutions.
Stokvels. According to the National Stokvel Association of South Africa (NASASA), there are about 800,000 stokvels with 11 million members; the same report puts their savings at an estimated R50 billion a year, without naming a source for that figure. The figures are estimates rather than audited totals; no one counts informal groups precisely. Stokvels have a recognised place in South African banking law: the Prudential Authority lists exemptions from the Banks Act for stokvels and savings and credit groups with a common bond, subject to conditions. In 2025 the Authority fined NASASA's financial co-operative R100,000 for breaching the conditions of its registration, a reminder that formalising the informal brings formal obligations.
Chamas. Kenya's 2024 FinAccess Household Survey, run by the Central Bank of Kenya and partners, found mobile money to be the most common way to save, used by 35.9% of Kenyans, with chamas next at 19.7%. Roughly one Kenyan adult in five, in other words, keeps savings in a group that runs on members' word.
Susu. Ghana's susu collectors collect daily deposits from clients and return the accumulated sum at the end of the month, keeping one day's deposit as their fee, as a 2025 analysis by the Ghana Fintech and Payments Association described it. The same analysis notes that 36% of Ghanaian women now save formally, citing the 2025 Global Findex, so susu increasingly sits alongside bank and mobile money accounts rather than instead of them.
Why repayment holds without collateral
Economists have studied rotating savings and credit associations (ROSCAs) for decades. In a much-cited 1993 paper in the American Economic Review, Timothy Besley, Stephen Coate and Glenn Loury modelled the economics of ROSCAs and showed why they make sense for people without access to credit: every member except the last to receive the pot gets the money earlier than they could by saving alone. The paper also took seriously the obvious weakness. A member who has already collected the pot has an incentive to stop paying.
What stops them is not a contract. It is the cost of being known as the person who stopped paying, among people they will deal with for years. The economist Marcel Fafchamps, in his study of market institutions in sub-Saharan Africa, took the difficulty of enforcing contracts as his unifying theme, and found market exchange in the region relying more heavily on social networks and personal trust than in richer economies.
Look at what these groups have in common and four mechanisms stand out:
- Small, frequent obligations. A daily or weekly contribution is small enough to pay and frequent enough that a missed payment is noticed at once.
- Members who already know each other. Colleagues, neighbours, church members, traders in the same market. The group admits people whose behaviour it can observe.
- A shared future. Members will keep meeting. Defaulting on the group means defaulting on a social life.
- Visible order. Everyone knows who has received the pot and who is still owed. There is no hidden balance sheet.
None of these requires a credit bureau. All of them require the group to be bounded.
What this means for B2B credit
Trade credit between businesses (a supplier shipping on 60 days, a buyer advancing a deposit before production) faces the same problem a chama solves: how do you trust someone to pay later when you cannot easily force them to? The informal groups suggest four lessons.
Lesson 1: build the record in small steps
A stokvel does not hand a new member the pot in month one. Trade relationships should not either. The equivalent in business is sequencing: a first order on prepayment or a confirmed letter of credit, a second on a deposit and cash against documents, credit only after a run of completed orders. Our guide on how to get paid safely when exporting from Africa sets out that ladder. Each completed order is a contribution paid on time.
Lesson 2: social collateral works inside the group, not across borders
The sanction that keeps a chama member paying is losing standing among people they see every week. A buyer in Rotterdam or a supplier in Lagos has no access to that sanction. They cannot exclude anyone from anything that matters to them. So the very mechanism that makes informal credit work does not transfer to cross-border trade.
This is the central limit, and it cuts both ways. An African supplier with years of impeccable conduct in its own networks starts from zero with a foreign buyer, because none of that standing is legible or enforceable abroad. And a foreign party cannot borrow the enforcement power of a network it does not belong to.
Lesson 3: the record usually exists only in people's heads
Most of the information that makes a member creditworthy (who paid on time, who covered for whom, who asked for an extension and honoured it) is held collectively and informally. That may change as groups move money through banks. South African banks now compete for stokvel deposits; Capitec, for example, is targeting the stokvel market. A group bank account leaves a record of money moving that a cash box does not.
Records are not the same as a credit history, though. A statement shows money moving; it does not show the obligation behind it, whether the payment was on time, or what the group would say about the member. Anyone tempted to treat informal-group membership as a credit score should notice how much of the signal is lost in that translation.
Lesson 4: the person in the middle is a point of failure
A susu works because clients trust the collector with their daily savings. If a collector disappears with the deposits, every client loses at once; the arrangement is only as sound as the person at its centre. Trade has the same weak point: the agent, broker or intermediary who sits between buyer and seller and handles documents or money. The lesson is to check intermediaries as carefully as counterparties, and to keep money and title documents moving through channels you control. Our guide to finding and checking a local partner covers how.
What a buyer or supplier can actually do
The practical question is how to use the logic of informal trust without pretending to have access to the network.
Ask for evidence of repeated performance. References from other buyers or suppliers the company has dealt with more than once are the closest business equivalent of a chama's memory. One reference from a single transaction is weak; three repeat relationships are strong.
Look for formal bodies that do record behaviour. Cooperatives, exporter associations and commodity boards often keep membership and delivery records. A cocoa or coffee cooperative's records of who delivered what, and when, are a documented version of the reputation a group holds informally.
Use payment structures that substitute for social collateral. Since you cannot exclude a defaulter from anything, make default costly or impossible by design: deposits, documents held until payment, bank undertakings, credit insurance. These are the formal equivalents of the shared future that keeps a stokvel member paying.
Do not ask for what you have no right to. A counterparty's personal participation in a savings group is their private financial life. If someone offers it as context, it may tell you something about discipline. It is not a basis for a business credit decision, and requesting such information raises consent and data protection questions. Our guide to KYC in Africa covers what due diligence can properly ask for.
Where the analogy breaks
It is tempting to romanticise informal finance. Three cautions.
Scale. A group works because it is small and its members are observable. Business credit often involves amounts far larger than any group's pot, between parties who will never meet.
Selection. Groups admit people they already trust and exclude others. That is efficient for the group and invisible to everyone outside it. Those who never got in have no record at all.
Pressure. The same social pressure that secures repayment can be harsh on members facing genuine hardship. Enforcement through reputation is not gentler than enforcement through courts; it is just different.
The argument in one paragraph
Informal savings groups show that the disposition to repay, and the habits that sustain it, are common across Africa and do not depend on formal credit infrastructure. What they do not show is that this trust can be exported. The mechanism that makes it work, bounded membership and an enforceable social cost of default, is precisely what a cross-border counterparty lacks. The task for international trade is therefore not to read informal networks directly, but to build its own short, observable, repeated record, with payment terms that protect both sides while that record accumulates. That is how a stokvel treats a new member, and it is a sensible way to treat a new trading partner.
AfroSynergy connects international buyers with African exporters. Listings open on 15 January 2027. To source a product or find a counterparty now, send us an enquiry.